
Mexico enters September 2026 with three genuinely positive macroeconomic signals: the peso appreciated to two-year lows versus the dollar, inflation continues its descent, and consumer confidence hit its best level in 10 months. However, the underlying picture that matters for B2B credit management remains unchanged: manufacturing continues contracting annually, registered employers fell again, and Banxico holds rates at 6.50% with upside risks in services inflation. Macroeconomic improvement is not being distributed evenly across sectors.
Executive Summary of Mexico's Economic Activity
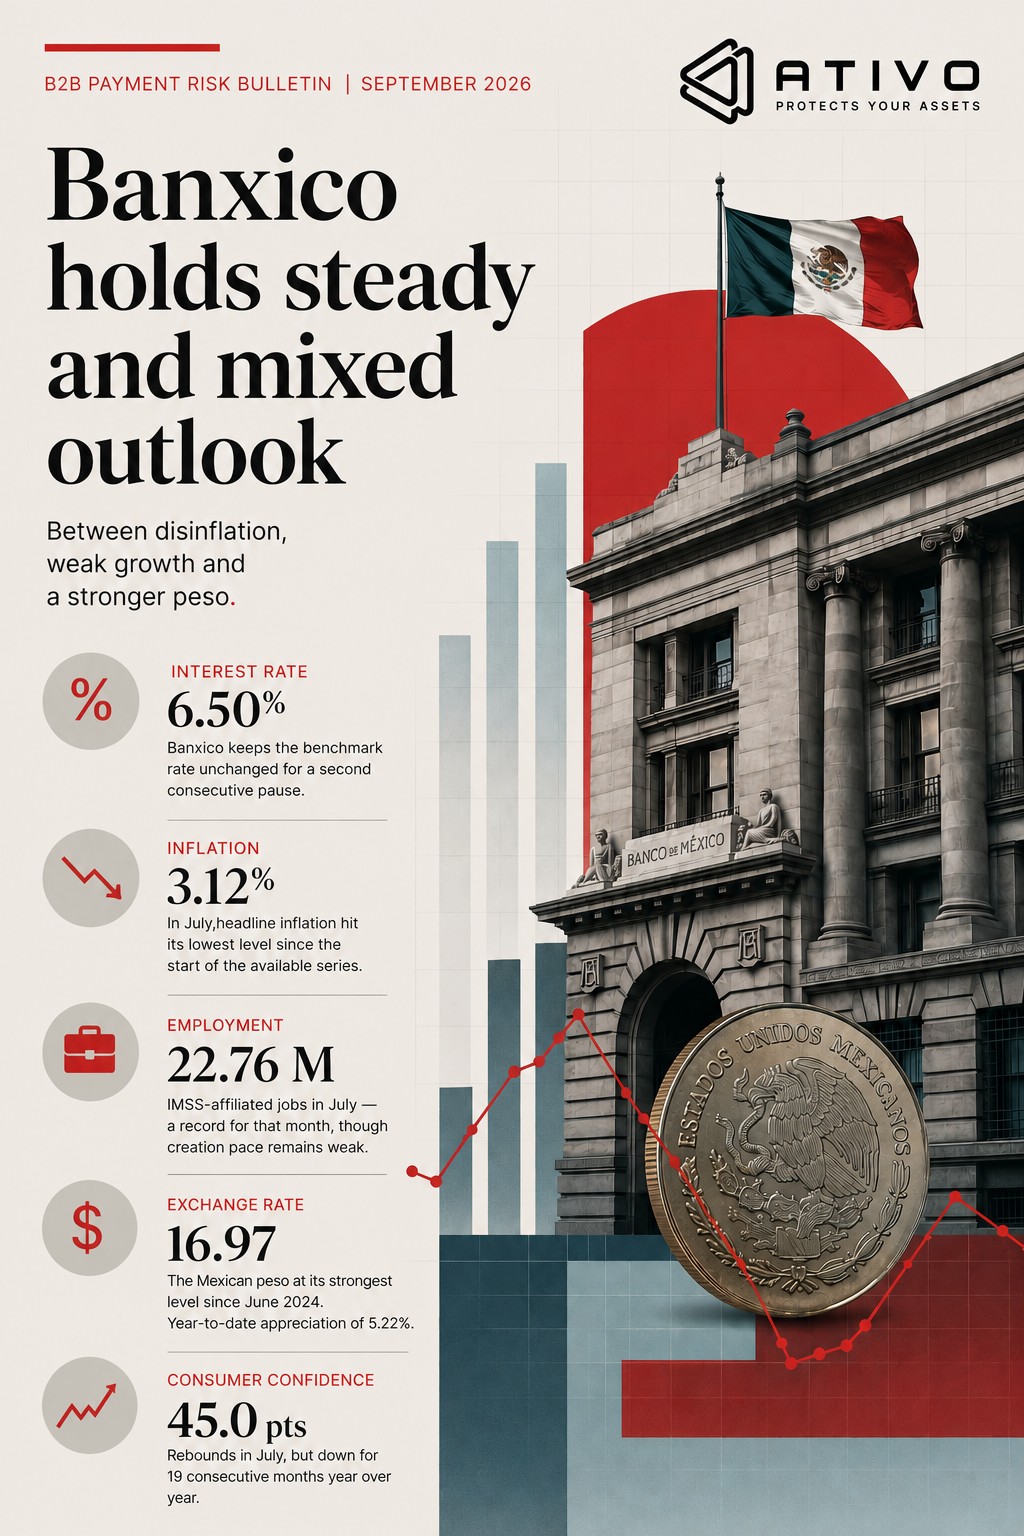
Banxico held the benchmark rate unanimously at 6.50% on August 6 — its second consecutive pause — and the minutes published August 20 confirmed the Board considers it appropriate to maintain this level for a prolonged period. The central bank pushed back its 3% inflation target deadline to Q4 2027, citing persistent services inflation and geopolitical risks. The next decision is September 24; HSBC projects the rate unchanged through end-2027. Annual headline inflation closed July at 3.12%, edging up to 3.26% in the first half of August, with core at 3.93% — the key concern for Banxico. The Citi survey projects a rebound toward 4.00% by year-end 2026.
The IGAE for June posted a monthly decline of -0.1% and annual growth of 1.7%. Within the report, manufacturing fell 1.2% annually in June — its worst recent monthly reading — while construction surprised with +4.2% annual growth. The January-June accumulation for secondary activities is flat at zero. On employment, July closed at 22,760,154 IMSS-registered jobs — a record for that month — but posted a monthly decline of 19,550 due to seasonality. The January-July cumulative total of 243,078 new jobs is well below the 100,000-per-month target, and registered employer units fell 2.5% annually.
The standout variable for September is the exchange rate: the peso appreciated to MXN 16.97/USD in August — the strongest level since June 2024 — accumulating a 5.22% gain year-to-date. Kapital, Monex, and HSBC project moderate depreciation toward year-end (range: MXN 17.29–17.88/USD). Consumer confidence rebounded to 45.0 points in July (+1.1 monthly) — its best reading since October 2025 — yet it has posted 19 consecutive months of annual decline, reflecting a structural caution pattern in private consumption.
Key Indicators
- Banxico benchmark rate: 6.50% — second consecutive unanimous pause; prolonged hold confirmed in Aug. 20 minutes. Next meeting: September 24 (Banxico / LatinUS).
- Annual headline inflation: 3.12% in July; 3.26% in 1st half of August — mild uptick but within target (INEGI).
- Core inflation (1st half August): 3.93% annual — persistent in services; limits rate cut window (INEGI).
- IGAE June: -0.1% monthly / +1.7% annual — manufacturing -1.2% annual; construction +4.2% annual (INEGI).
- Formal employment IMSS (July): 22,760,154 jobs — record for July; -19,550 monthly (seasonal); 2026 cumulative: 243,078 (IMSS / STPS).
- Consumer Confidence Index (ICC, July): 45.0 points (+1.1 monthly; -0.7 annual) — best in 10 months; 19 consecutive annual declines (INEGI).
- Exchange rate: MXN 16.97/USD low in August — 5.22% YTD appreciation; year-end projection: MXN 17.29–17.88 (BASE / HSBC / Monex).
- Next Banxico meeting: September 24, 2026 — consensus: hold at 6.50%; HSBC projects unchanged through end-2027.
Default Risk Outlook by Sector
Manufacturing & Transformation Industry — 🔴 High Risk
Manufacturing posted a 1.2% annual contraction in June's IGAE — its worst recent monthly reading — and the H1 cumulative for secondary activities is flat at zero. A strong peso raises the effective cost of Mexican exports and compresses margins for U.S.-facing producers, with 10% U.S. tariffs on Mexican exports still in place. Industrial input suppliers and export-linked supply chains remain in the highest-risk segment for B2B trade credit defaults.
Agriculture & Agro-Industry — 🟡 Moderate Risk
Primary activities show improved momentum, with construction-adjacent agro activity positive in June. However, seasonal employment declines in July and commodity price volatility can compress agro-industrial margins. Risk remains moderate, with continued monitoring required for input suppliers and processors.
Construction & Building Materials Supply — 🟡 Moderate-High Risk
Construction surprised with 4.2% annual growth in June's IGAE — the best sector reading in months — but private investment recovery is not yet consolidated. Materials distributors should maintain vigilance for smaller-scale private developers and mid-market real estate projects where cash flows remain stretched.
Wholesale Trade & Domestic Consumption — 🟡 Moderate-High Risk
Consumer confidence rose to 45.0 points in July — best in 10 months — but 19 consecutive months of annual decline reveal a structural caution pattern. Retail commerce fell 0.4% annually in June's IGAE. Wholesale distributors of discretionary goods remain exposed to payment deferrals and credit term renegotiations.
Exporters & Companies with Dollar-Denominated Debt — 🔴 High Risk
The strong peso (MXN 16.97/USD in August) creates a dual risk: exporters see the peso value of USD revenues compressed, squeezing margins; and the projected depreciation toward year-end may deteriorate the position of companies with dollar-denominated debt. Both dynamics generate short-to-medium-term payment capacity risk that deserves close monitoring.
Services, Healthcare & Essential Consumption — 🟢 Low Risk
Hospitality and food services contracted 3.1% annually in June's IGAE — a post-World Cup normalization — but healthcare, education, and essential consumption maintain stable demand and the best relative payment behavior. Core services inflation at 3.93% compresses margins but does not threaten fundamental demand.
Three Warning Signals in B2B Credit Operations
- Your client exports or earns revenues in U.S. dollars and has recently reported tighter peso liquidity despite "strong sales" — the strong peso is compressing the peso value of USD collections, which may translate into delays in payments to domestic suppliers.
- Your manufacturing buyer has reduced production orders without any change in headcount or apparent activity — a signal of anticipatory inventory adjustment ahead of continued sector weakness, with a predictable cash flow impact in the next 4–6 weeks.
- You are receiving requests for payment extensions or method changes from clients who have historically been punctual — in an environment where Banxico holds at 6.50% and bank credit remains restrictive, external financing access for your clients is more expensive and constrained than it appears.
Key Recommendation
⚡ Use the September 24 Banxico decision as your portfolio review deadline. Before September 24, identify the manufacturing and export clients that represent the largest balances in your accounts receivable and assess their exposure to exchange rate movements, tariffs, and bank credit access. Confirm the status of outstanding invoices, update accounts payable contacts, and define early warning thresholds for Q3 close. In an environment where macroeconomic conditions improve but sector risks persist, timely receivables recovery is what separates growing companies from those absorbing write-offs. If your internal team lacks capacity for this level of management, consider the support of a specialized B2B collections partner like ATIVO.
Conclusion
September arrives with the best macroeconomic backdrop of the year — inflation on target, a strong peso, and consumer confidence rising — but manufacturing data, employer registrations, and exchange rate dynamics warn that improvement is not uniform. For B2B companies extending trade credit, this is the moment to conduct a portfolio health check before Q3 closes and to activate preventive collection with enough lead time to recover before sector risks translate into defaults.
Is your B2B receivables portfolio ready for Q3 close?
→ At ATIVO we help you recover accounts receivable before they escalate — Free consultation📧 info@ativo-mx.com · 📞 +52 55-7583-9900
ATIVO — Collection Specialist in Mexico. We represent international creditors in the recovery of B2B debt with Mexican companies. Free initial consultation available.